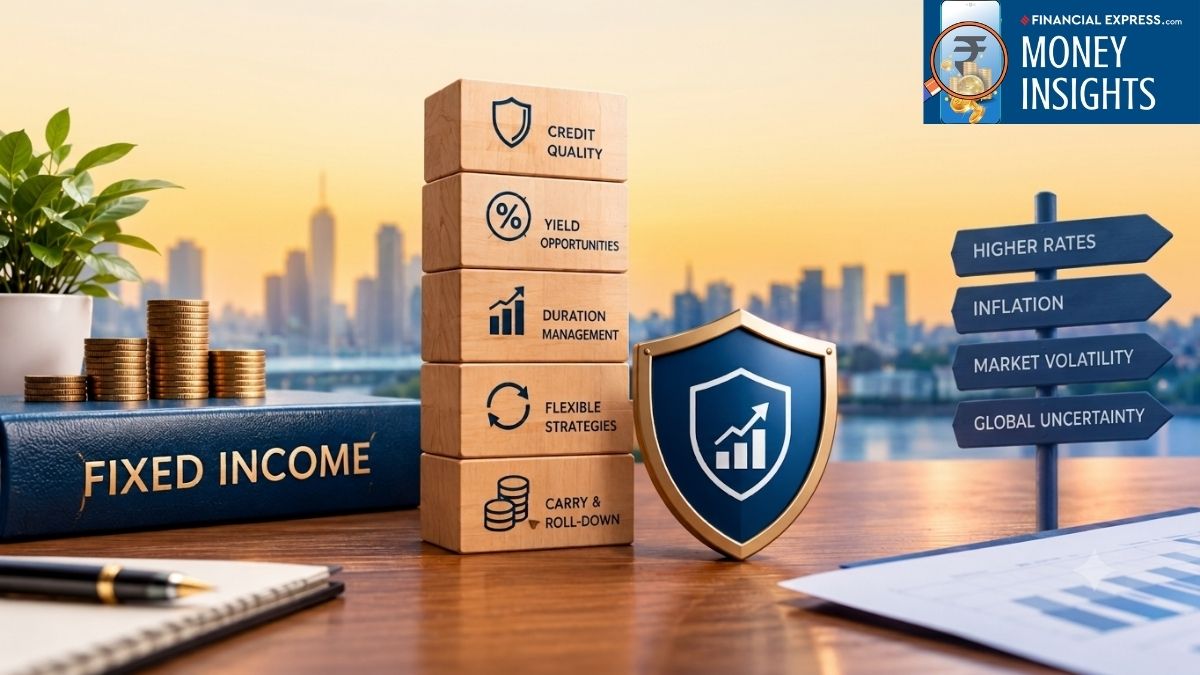
How to Build a More Resilient Fixed Income Portfolio
Recent central bank policies highlight a higher-for-longer interest rate environment, prompting fixed income investors to reassess portfolio duration, credit quality, and risk management amid ongoing market uncertainty.
Recent policy actions from major central banks have again brought interest rates into focus. Whether it is the Reserve Bank of India (RBI) maintaining a firm stance on inflation risks or the US Federal Reserve (Fed) signaling that policy may need to remain restrictive for longer, bond markets globally continue to adjust to a higher-for-longer interest rate environment. For fixed income investors, periods such as these often warrant a review of portfolio exposures.
Not necessarily because an immediate change is required, but because the backdrop that worked in one rate cycle may not hold in another. The challenge today is not merely the level of rates. Rather, it is the degree of uncertainty surrounding their future trajectory. Bond Markets and the Repricing of Expectations Bond yields are driven not only by current policy rates but also by expectations regarding future inflation trajectory, growth and central bank actions regarding policy rates.
As these expectations evolve, bond markets periodically reprice. In such environments, volatility in fixed income markets may appear counterintuitive. Bonds are generally perceived to be associated with lower volatility, yet periods of policy uncertainty can lead to meaningful fluctuations in prices, particularly in longer-duration segments of the market. This dynamic has been visible across global bond markets in recent years.
Episodes where investors anticipated imminent rate cuts have often been followed by renewed concerns around inflation persistence or fiscal pressures, resulting in repeated adjustments in yield expectations. The Question Is Not Whether Rates Rise or Fall One of the commonly occurring considerations in fixed income investing is to anchor portfolios around a single interest-rate outcome. But markets generally don’t tend to move in a straight line.
Even during broader easing cycles, yields can periodically rise. Similarly, during tightening phases, sections of the yield curve may behave differently than expected. As a result, portfolio construction may warrant greater attention than rate forecasting itself. The focus, in many cases, shifts from attempting to anticipate the next policy move towards assessing whether the risks embedded within a portfolio remain commensurate with the investor's objectives and investment horizon.
Duration Risk Deserves Closer Attention In periods where rate expectations remain fluid, duration becomes increasingly relevant. Longer-duration portfolios tend to exhibit more sensitivity to changes in bond yields. While such exposure may benefit portfolios if yields decline materially, the same characteristic could contribute to elevated mark-to-market volatility if rates remain elevated or rise further.
This does not imply that longer-duration strategies are inappropriate. Rather, it highlights the importance of understanding the role they play within an overall portfolio. For investors with shorter investment horizons or lower tolerance for interim volatility, strategies positioned at the shorter end of the maturity spectrum may offer a different risk-return profile compared with longer-duration alternatives.
Yield Alone May Not Provide the Complete Picture Periods of elevated interest rates often bring another visible feature: higher advertised yields. While attractive yields naturally draw investor attention, the source of those yields warrants equal scrutiny. In fixed income, incremental yield may arise from several factors, including: Longer maturity exposure; Lower credit quality; Reduced liquidity; or Structural portfolio positioning.
Viewed in isolation, a higher portfolio yield may provide only a partial picture. A useful question for investors may not be - whether a particular portfolio offers a higher yield, but rather what risks are being undertaken to generate that additional yield. Credit Quality Remains a Key Consideration Interest-rate risk tends to be immediately visible through changes in market prices. Credit risk, by contrast, often emerges gradually.
As a result, periods of market adjustment can reinforce the importance of understanding the quality profile of underlying holdings. Investors evaluating debt strategies may wish to consider whether additional return expectations are being derived from duration positioning, credit exposure, or a combination of both. Where interest-rate volatility is already a feature of the environment, some investors may prefer to understand whether additional layers of risk are also being introduced.
The objective is not to avoid risk altogether but to ensure that risks are deliberate, understood and aligned with the intended role of the allocation. Carry and Roll-Down: Returning to Fixed Income Fundamentals In recent years, discussions around fixed income have frequently centered on duration calls and policy expectations. However, in a higher-yield environment, traditional sources of bond returns such as carry and roll-down may regain prominence.
Carry represents the income generated from holding a bond portfolio over time, while roll-down reflects the impact of bonds moving closer to maturity along the yield curve. When yields are elevated relative to recent history, these return drivers may contribute meaningfully to overall outcomes, even in the absence of capital appreciation. For this reason, strategies that seek to capture carry while maintaining disciplined risk management continue to attract investor attention across market cycles.
Dynamic bond strategies, given their flexibility, may have the ability to alter duration based on evolving market conditions. The potential advantage of such an approach lies in adaptability. However, outcomes remain dependent on portfolio positioning, investment discipline and the accuracy of underlying assessments. Accordingly, investors evaluating such strategies may find it useful to examine not only performance outcomes but also the consistency of investment processes, portfolio construction framework and risk management practices.
The current rate environment may not necessarily call for major portfolio changes. It may, however, justify asking a number of important questions. Is the portfolio's duration exposure consistent with the investment horizon? Is additional yield being generated through maturity risk, credit risk, or both? Does the strategy rely on a specific interest-rate outcome? Are risks adequately diversified? Is the portfolio positioned to navigate multiple scenarios rather than relying on a single market outlook?
The answers are likely to vary across investors. Central bank actions tend to attract attention because they impact borrowing costs, economic activity and market sentiment. For bond investors, however, the more relevant consideration may be how those actions alter the balance between risk and return. In an environment characterized by evolving inflation dynamics, shifting global yield expectations and periodic market volatility, portfolio resilience may become as important as return expectations.
The coming quarters may bring higher rates, or periods where markets oscillate between the two narratives and remain rangebound. What remains constant is the importance of understanding where returns are expected to come from, and equally, the risks associated with achieving them. Sneha Pandey is Fund Manager for Fixed Income and Multi-Asset Allocation Funds at Quantum AMC Disclaimer, Statutory Details & Risk Factors: The views expressed here in this article are for general information and reading purpose only and do not constitute any guidelines and recommendations on any course of action to be followed by the reader.
Quantum AMC / Quantum Mutual Fund is not guaranteeing / offering / communicating any indicative yield on investments made in the scheme(s). The views are not meant to serve as a professional guide / investment advice / intended to be an offer or solicitation for the purchase or sale of any financial product or instrument or mutual fund units for the reader. The article has been prepared on the basis of publicly available information, internally developed data and other sources believed to be reliable.
Whilst no action has been solicited based upon the information provided herein, due care has been taken to ensure that the facts are accurate and views given are fair and reasonable as on date. Readers of this article should rely on information/data arising out of their own investigations and advised to seek independent professional advice and arrive at an informed decision before making any investments. Mutual Fund investments are subject to market risks, read all scheme related documents carefully.